Financial Reporting Services: What They Are & Why You Need Them
If you run a business in Australia, you’ve probably wondered whether it’s time to bring in financial reporting services instead of managing everything yourself.
Read article →
A family trust is commonly a discretionary trust where a trustee holds and manages assets for beneficiaries, usually within the same family group.
Many families use a family trust structure to organise investments, operate a family business, and distribute income in a tax-efficient way. Understanding how these trusts operate, their advantages, and how to set up a family trust is important before establishing this type of trust arrangement.
A family trust in Australia is a legal arrangement where a trustee manages assets on behalf of beneficiaries according to the rules outlined in a trust deed. This structure is commonly used by families to manage wealth, investments, and family businesses. In most cases, a family trust is established as a discretionary trust, meaning the trustee decides how trust income is distributed among beneficiaries each financial year, subject to the trust deed and any required trustee resolutions.
This flexibility allows families to manage shared assets and distribute income based on financial circumstances. For business owners, a family trust may support tax planning by allowing income to be allocated among beneficiaries within the family group, where permitted by the trust deed and tax rules.
A family trust allows assets to be held by the trustee on trust rather than owned directly by individuals. The trustee manages the trust assets and distributes trust income to beneficiaries according to the rules defined in the trust deed.
In many cases, beneficiaries are assessed on trust income to which they are presently entitled, while the trustee may be taxed in some circumstances, including where income is not effectively distributed. Beneficiaries generally report their share of trust income in their personal tax returns and pay tax based on their marginal tax rates, where they are presently entitled. This structure is widely used by families managing shared investments, property portfolios, or family businesses.
At the end of each financial year, the trustee decides how trust income will be distributed among beneficiaries within the defined family group, subject to the trust deed and any required trustee resolutions. This decision must comply with the trust deed and Australian tax requirements, including any timing rules for effective resolutions. The trustee considers the circumstances of beneficiaries when determining distributions.
The top marginal tax rate in Australia is 45% plus a 2% Medicare levy, resulting in an effective rate of approximately 47% depending on individual circumstances. Because beneficiaries may have different tax rates, distributing income within the family group may help improve tax efficiency, although outcomes depend on the deed, beneficiary circumstances, and anti-avoidance rules.
Example distribution scenario:
| Beneficiary | Marginal Tax Rate | Distribution Outcome |
|---|---|---|
| Parent (high income) | 45% top marginal tax rate* | Smaller distribution |
| Adult child | 19% | Larger distribution |
| Spouse | 30% | Moderate distribution |
Beneficiaries who are presently entitled to trust distributions are generally responsible for paying tax on their share of trust income. They must include these distributions in their personal tax return and pay tax according to their marginal tax rate. If income is retained rather than distributed, the trustee may be taxed at the top marginal individual rate on undistributed income.
Trustees must ensure distributions and reporting comply with Australian Taxation Office (ATO) requirements, including valid trustee resolutions where applicable.
Tax considerations are one reason families and business owners explore family trust structures. In discretionary trusts, income is usually distributed to beneficiaries each financial year, and those beneficiaries are generally responsible for paying tax on their allocated share if they are presently entitled.
Important tax considerations may include:
Because trust taxation rules can be complex and vary depending on individual circumstances, families often seek professional advice or guidance from the ATO when making tax planning decisions.
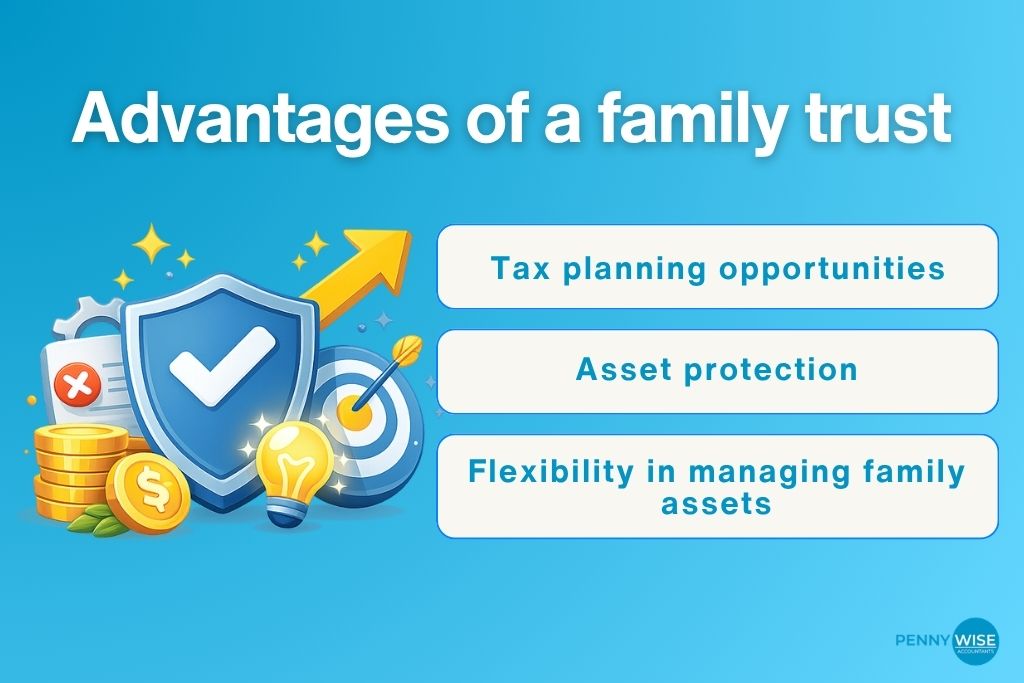
Many families and business owners consider establishing a family trust because it can offer structural and financial advantages.
A discretionary trust may allow income to be distributed among beneficiaries with different marginal tax rates, subject to the trust deed and tax law. When managed within tax law requirements, this flexibility may help improve overall tax efficiency across the family group.
Assets held within a trust are held by the trustee on trust rather than by individual family members personally. Depending on the circumstances, this separation may provide some protection from certain business risks or creditor claims, but it is not guaranteed.
A family trust provides flexibility in managing investments and income distributions. Trustees may adjust distributions annually depending on financial circumstances, which can assist families managing investments, property, or business income.
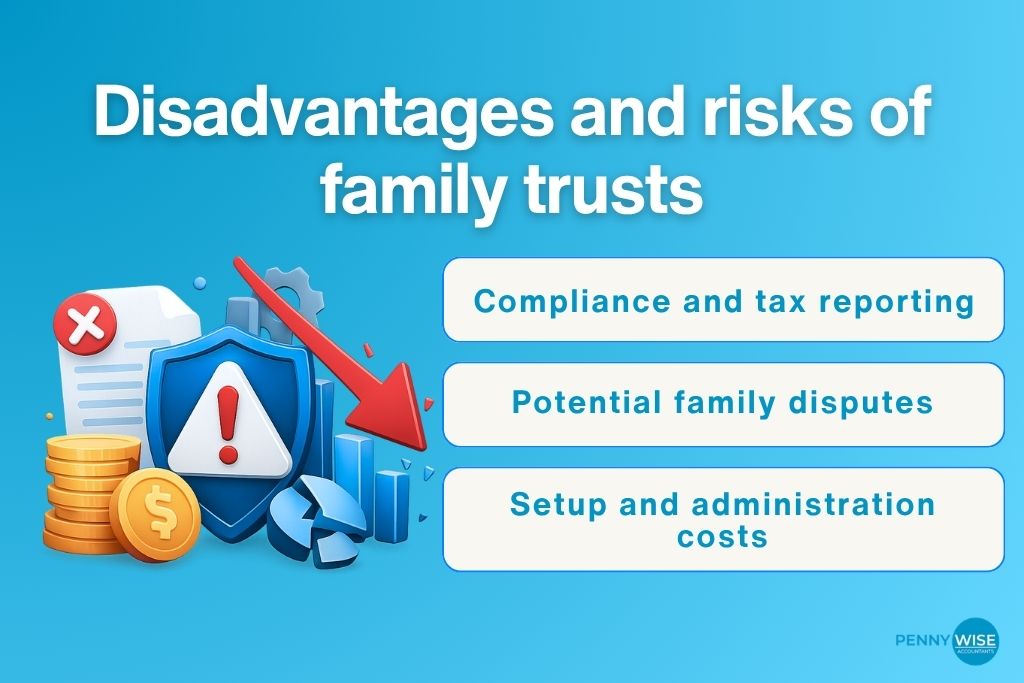
Although family trusts offer potential advantages, they also involve responsibilities and possible risks.
Trusts generally must maintain financial records and lodge annual tax returns with the ATO where required. Trustees are responsible for ensuring the trust complies with relevant tax and legal obligations.
Because the trustee controls income distributions, disagreements between beneficiaries may arise. Clearly defined responsibilities in the trust deed and transparent communication between family members can help reduce the likelihood of disputes.
Establishing a trust structure requires legal documentation, such as preparing a trust deed and registering the trust for tax purposes. Initial setup costs can vary widely and are often quoted as a market estimate rather than a fixed fee.
Ongoing administration may include accounting services, trust tax returns, and compliance reporting, with annual costs varying by trust complexity and adviser fees.
A family trust may be suitable for families who want to manage assets collectively, operate a family business, or plan succession, depending on their tax and legal circumstances.
This structure is often used for:
Family trusts may also support long-term financial planning and succession planning across generations. However, whether a trust structure is appropriate depends on financial circumstances, tax considerations, and compliance requirements. Seeking professional accounting or legal advice may help families determine whether a trust aligns with their financial objectives.
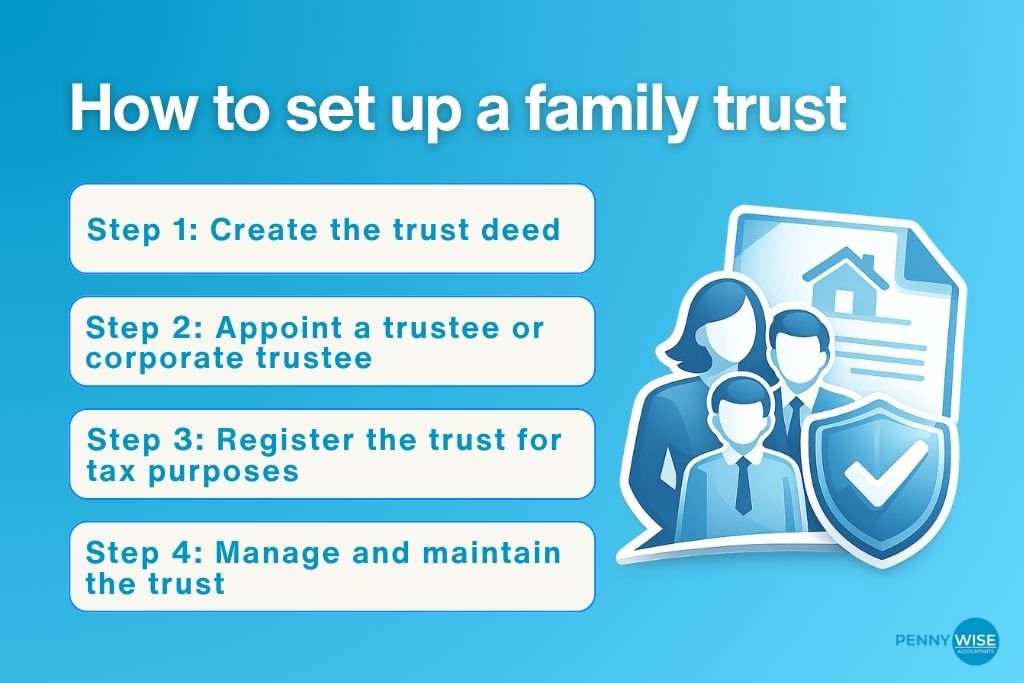
Setting up a family trust involves several key steps to ensure the trust is legally established and compliant with tax requirements.
The trust deed is the legal document that establishes the trust and outlines how it operates. It identifies the beneficiaries, defines the powers of the trustee, and sets the rules for managing and distributing trust income and assets. Once the deed is properly executed and settled, the trust is formally created.
The trustee is responsible for managing the trust and its assets. This role can be held by an individual or a company acting as a corporate trustee. A corporate trustee is often used to help maintain a clearer separation between personal and trust assets, but it is optional rather than mandatory.
After the trust is created, the trustee should arrange the trust’s tax registrations, including a TFN and, if applicable, an ABN. This usually includes applying for a TFN and, where the trust is carrying on an enterprise and is entitled, an ABN.
Once established, the trustee must manage the trust according to the trust deed and make valid annual distribution decisions where required. This includes keeping financial records, preparing annual accounts, lodging tax returns, and distributing trust income to beneficiaries each year.
A family trust can be a useful structure for families and business owners who want to manage assets, distribute income, and support long-term financial planning. It offers flexibility in allocating income among beneficiaries while helping organise investments or operate a family business. However, trustees must understand the legal responsibilities and tax obligations involved.
In our work with clients at Pennywise Accountants, we often see families explore trust structures when planning how to manage income, investments, or business activities. Because each situation is different, reviewing the trust deed, tax implications, and compliance requirements is important before making decisions. Understanding how a trust fits within a broader financial strategy can help families make informed choices.
Setting up a family trust may cost around this range in the market, but the actual cost depends on the trust deed, legal work, and whether a corporate trustee is used. Ongoing administration and accounting costs vary depending on the trust’s complexity and adviser fees.
Yes, a family trust can own property, shares, or business assets through the trustee acting on behalf of the trust. Many families use trusts to hold investment properties, share portfolios, or operate family-owned businesses.
A family trust generally distributes income to beneficiaries who may be assessed on their share where they are presently entitled. A company pays tax on its profits before distributing dividends to shareholders. Trusts offer flexibility in income distribution, while companies operate under a fixed ownership structure.
Yes, the trustee can usually be replaced if the trust deed allows it, and the appointor or equivalent control mechanism often governs the process.
Yes, family trusts generally lodge annual trust tax returns where required, and the return reports income, expenses, and distributions.
Yes, a family trust can continue operating after the original trustee passes away. The trust deed usually specifies how a new trustee can be appointed to ensure the trust continues managing assets.
Children can be beneficiaries of a family trust, but special tax rules apply to minors under 18. Under Division 6AA of the Income Tax Assessment Act 1936, unearned income above certain thresholds may be taxed at higher rates unless an exception applies.
A family trust operates until its vesting date, which depends on the trust deed and applicable state or territory law; in many cases the period may be long, but it is not universally 80 years across Australia.
This article is general information only and does not constitute personalised tax or financial advice. Speak to a registered tax agent about your circumstances.
Book an initial call and we’ll talk through what it means for your numbers.
If you run a business in Australia, you’ve probably wondered whether it’s time to bring in financial reporting services instead of managing everything yourself.
Read article →
Managing small business tax accounting can be one of the most stressful parts of running a business in Australia.
Read article →
If you run a business in Australia, you may be wondering what a BAS is and why it is important for tax reporting.
Read article →Trusted & Certified
 Pennywise Accountants is a CPA practice.